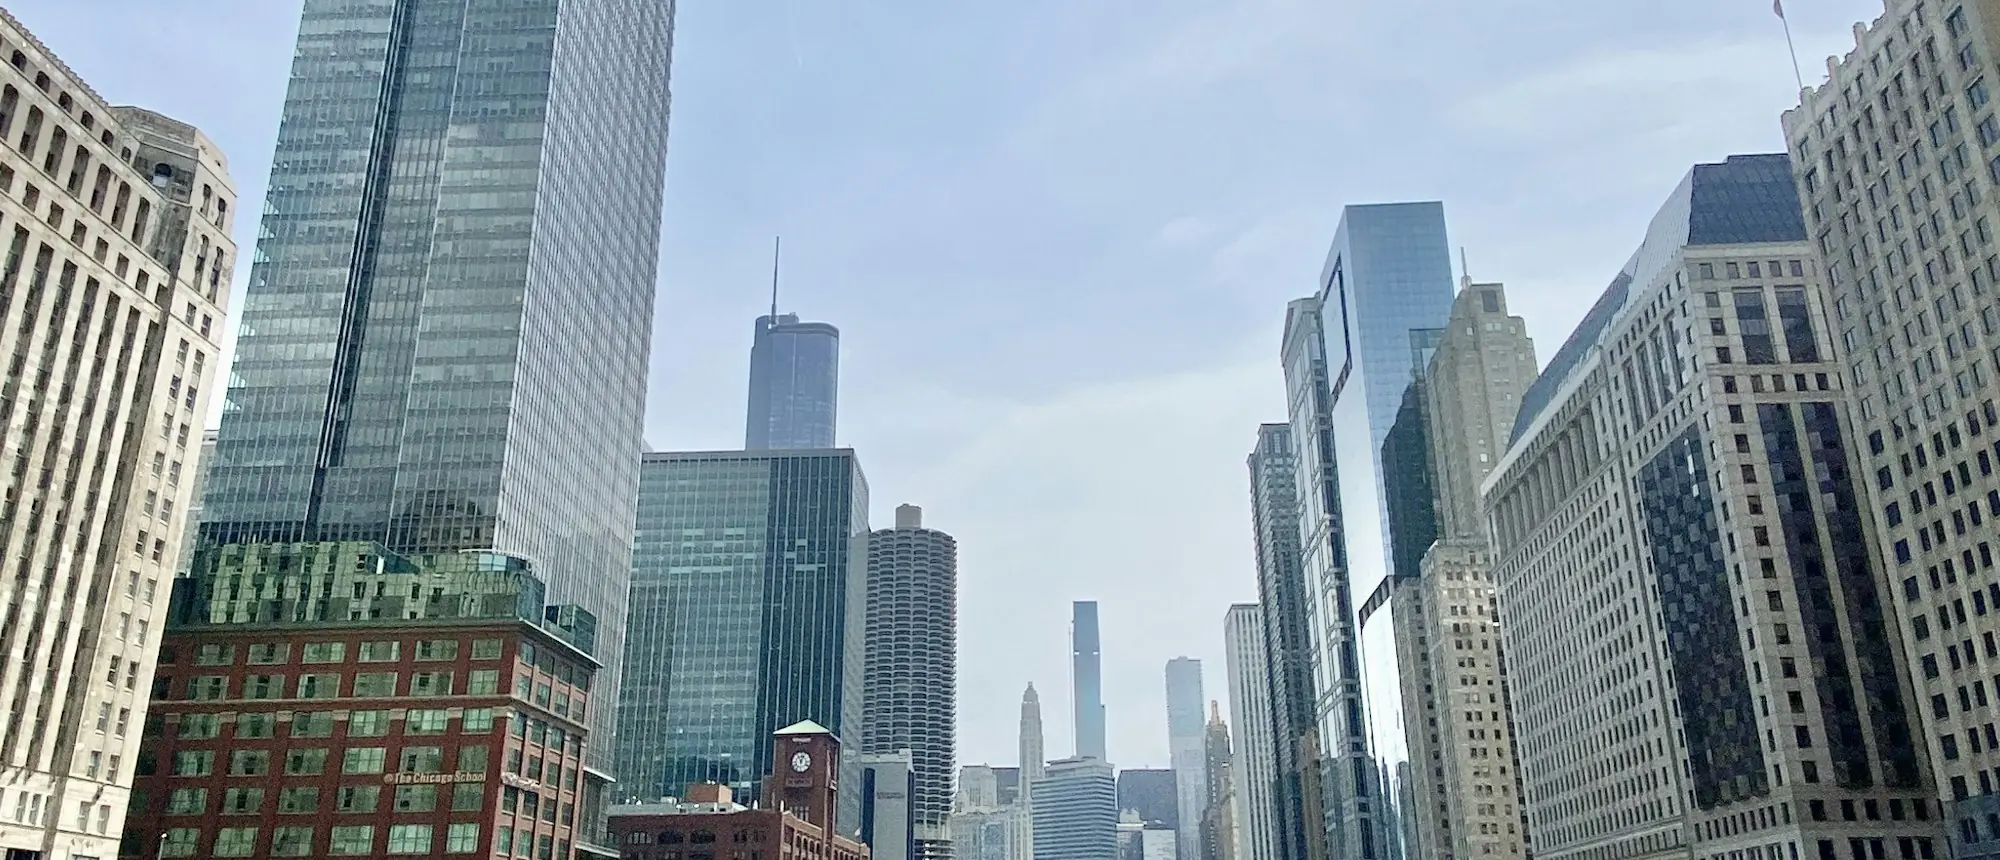
Chicago · 2027
Your lender said the building doesn’t qualify. That is a conventional-loan problem, not a dead deal. Olympus Financial finances the Chicago condos Fannie Mae and Freddie Mac won’t, through 80+ investors and a team trained to find a way.
Fannie Mae and Freddie Mac now put Chicago condo buildings through a full review of budgets, reserves, and insurance, and the reserve standard rises again on January 4, 2027. Buildings that passed last year are failing this year. What changed, with the agency sources →
Associations that budget lean, or never commissioned a reserve study, no longer pass.
Higher master-policy deductibles and coverage gaps now disqualify the whole building.
Open structural work, a special assessment, or a pending lawsuit stops a conventional loan.
Too much retail space, too many units under one owner, or hotel-style rentals.
None of it is about you. None of it has to stop the purchase.
A failed review means one thing: the loan can’t be sold to Fannie Mae or Freddie Mac. So we don’t send it there. We place it with investors who underwrite the building on its merits — for primary homes, second homes, and rentals, with W-2 income, bank statements, 1099s, assets, or the property’s own rent.
We have closed non-warrantable condo loans across Chicago and the suburbs, from lakefront high-rises to vintage courtyard buildings. Yours is not the first building like it we have seen.
Get a Straight AnswerNon-warrantable condos are a core product here, not an exception request. We built this practice in Florida, where condo buildings ran into these rules years before Chicago did.
Every investor treats reserves, litigation, and mixed-use differently. We know which one takes which issue, so your file lands on the right desk the first time.
Full documentation, bank statements, 1099s, assets, or rental income for investors. The building is unusual. Your loan doesn’t have to be difficult.
Send the address and what your lender told you. You get a clear yes, a clear no, or exactly what it takes — while your contract dates still hold.
From your first call to closing, the same team runs your file — no getting passed to a call center or a bank underwriter who’s never heard your name.
Already under contract? Tell us your dates. We work backward from your closing.
The address and what your lender told you. If you have the condo questionnaire or budget, even better. Sixty seconds on the form or one phone call.
We identify why the building failed and take it to the investors that accept that exact issue. You get real terms on your scenario, not a maybe.
One team runs the file from application to the closing table, and keeps you, your agent, and your attorney informed at every step.
A condo that fails review in week three costs you a contract and a client’s confidence. Send us the address before the offer, or the moment a lender declines. We tell you where the building stands and what it takes to keep your closing date.
Clear communication. Approvals that hold. Complex deals closed. That’s the Olympus standard for every referral partner.
Send a DealNot a call center. Not a ticketing system. Licensed Olympus loan officers who know Chicago buildings, pick up the phone, and don’t stop until it closes.
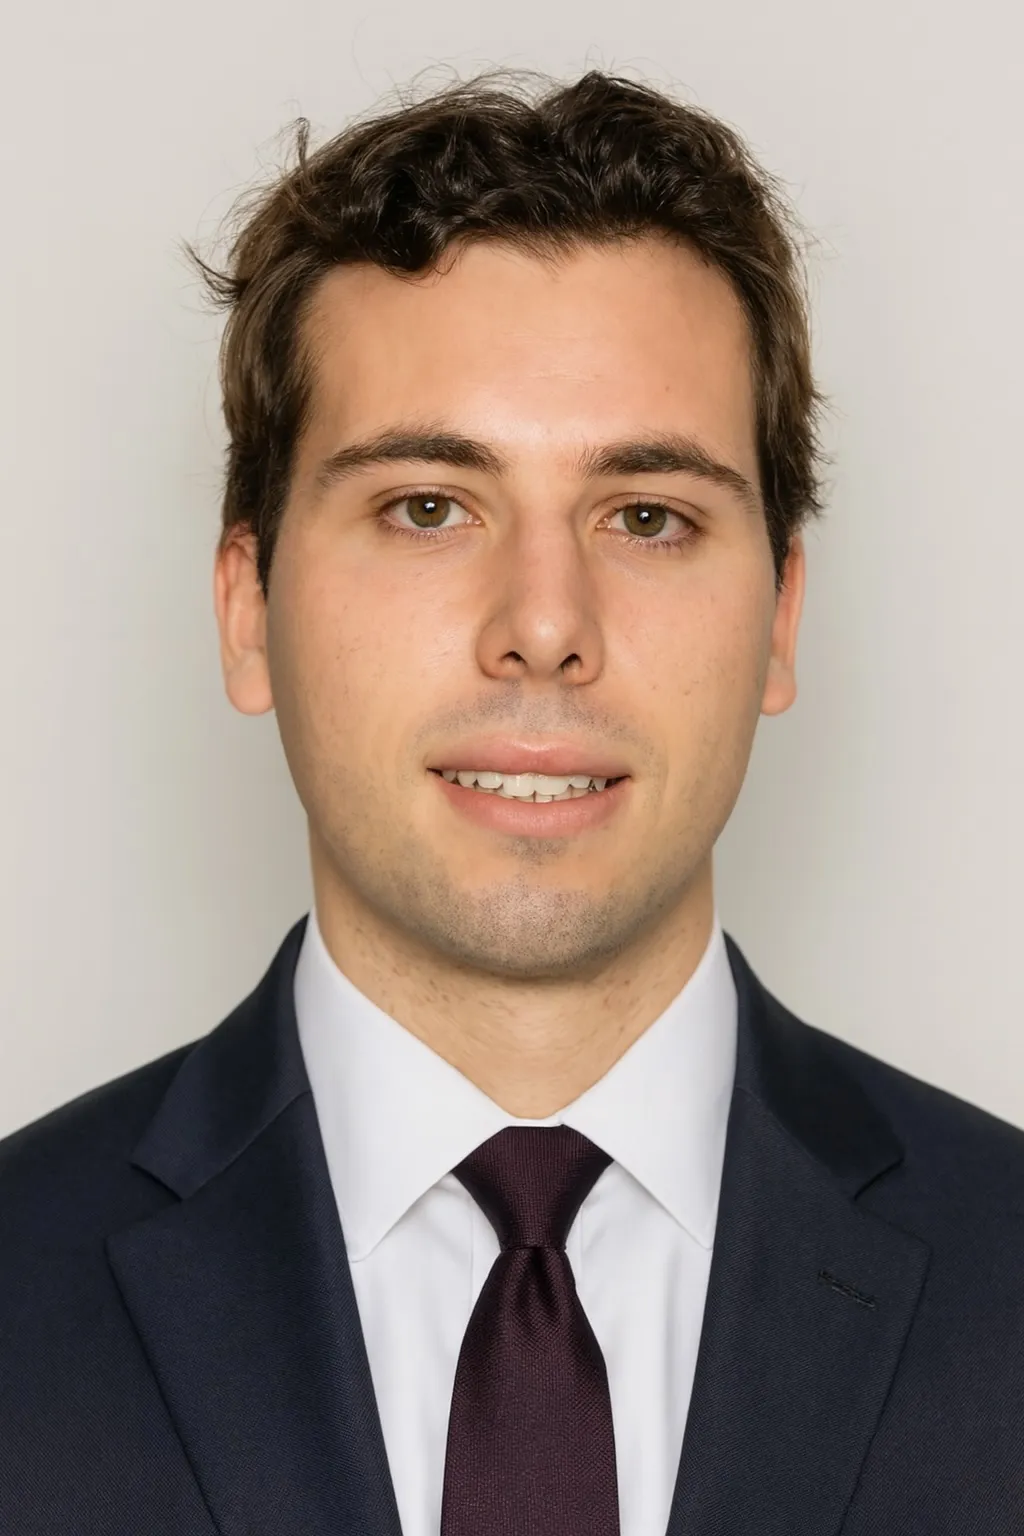
Olympus’s Chicago Condo Guru. Knows the buildings, the boards, and where conventional lenders stop.
Conventional, FHA, VA, and jumbo executed with precision. Non-QM, DSCR, and non-warrantable condo loans when the file is complicated. One company, 80+ investors, and a 5.0 Google rating earned one closing at a time.
About OlympusThe short version. For your building and your numbers, send us the address.
Yes. Olympus Financial is licensed in Illinois and finances non-warrantable condos in Chicago and the suburbs through investors that set their own building standards.
No. The decline applies to conventional financing on that building. Move quickly, keep your contract dates in view, and send us the building today.
You’d be surprised. For qualified applicants, non-warrantable financing can sit so close to conforming that you wouldn’t notice a difference. We put the real terms for your building and your file in front of you before you commit to anything.
Often, yes. If the association fixes what caused the building to fail and you qualify, a conventional refinance may be available down the road.
Send us the address and what your lender told you. We’ll tell you exactly what’s possible and get you moving fast.
Send Us the BuildingCall before it falls apart. One conversation tells you whether the building can close.
Call 888.709.4880Olympus Financial, LLC · NMLS #2469800 · Illinois Residential Mortgage Licensee · Serving Chicago and Chicagoland.
Not a commitment to lend. All loans subject to credit and property approval. Program availability and terms vary by investor; not every building or borrower qualifies. Reviewed by Josh Jankelow, President, NMLS #1857361 · Updated October 6, 2026.